
Four bits of fiber expansion news from around the US to catch up on: … [visit site to read more]
Four bits of fiber expansion news from around the US to catch up on: … [visit site to read more]
Telecom automation is moving beyond predefined tasks towards networks that can increasingly analyse conditions, make decisions and act autonomously. Self-configuration for provisioning, closed-loop optimisation, and automated fault recovery promise greater operational efficiency and reliability, while enabling services to be provisioned and adapted with less manual intervention.
The transition is already underway. According to a study by the IBM Institute for Business Value and TM Forum: Navigating autonomous networks, 73% of network executives surveyed said their organisations had developed phased roadmaps towards autonomous operations. Yet only 6% of CSPs reported operating highly autonomous Level 4 network instances. Within three years, 22% expect to reach that level.
What must change to bridge that gap? It starts with data. As a data transformation company, DFG CONSULTING focuses on the quality and trustworthiness of the physical network data that automation depends on.
When the network and its data diverge
Telecom networks have evolved continuously over decades, but the data describing them has not always kept pace. Network extensions, technology changes, mergers and system migrations have left many operators with information distributed across multiple systems and formats.
Critical network information may still reside in CAD or Visio drawings, PDFs, raster images and spreadsheets alongside central inventory systems. While valuable to engineers, this unstructured information cannot readily support automation.
The challenge goes deeper than format. Field changes are not always accurately reflected in the system of record, creating discrepancies between as-planned and as-built networks.
Missing or incorrect connectivity creates further uncertainty. Engineers and field teams may consequently maintain local “shadow documentation” to capture information that is missing, outdated or difficult to retrieve from the system of record.
The problem is therefore often not the absence of data, but whether operators can trust that it accurately represents the physical network and whether it is in the right form for growing network automation and autonomy.
The consequences of inaccurate data
Experienced engineers might still recognise when a network record does not reflect reality and question it before acting. Automated operations do not necessarily have that safeguard because they cannot recognise inaccurate data.
Physical assets do not have intelligence, telemetry, or at least some form of active communication. They cannot report their state. They cannot self-discover. They cannot tell an inventory system where they are, how they’re connected, or whether they were built to design. Automated decisions solely rely on a trustworthy, precise, end-to-end digital representation of all available physical assets.
Incorrect data can lead to an incorrect path calculation, affecting service provisioning or instructions for field teams. Inaccurate connectivity can result in flawed impact analysis and the wrong customers or services being identified during an outage.
Intelligent data migration
Recognising the need for trustworthy data is the easy part — the challenge is quality, scale, efficiency and continuity. Operators may hold hundreds of thousands of legacy files accumulated over decades, while new documentation keeps arriving, often incomplete, inconsistent or conflicting, and daily operations cannot pause while this data is transformed.
The question becomes: how can operators convert, validate, and reconcile network data at scale while updating operational data on the fly?
Physical network documentation is naturally fragmented across distinct views — spatial maps, schematics and splice diagrams — each describing the same elements at a different level of detail. Manually redrawing legacy files into operational support systems is common, but a more effective approach is to use a specialised tool Interactively Assisted Converter™ that extracts data from legacy drawings and structures it in a machine-readable format, ready for direct ingestion into the system of record.
This tool can cross-reference and merge disparate views into a single dataset, with AI adapting to the multiple drawing standards different data providers use. Data conversion is fundamentally a cleaning process: automation extracts, structures, and resolves quality issues for most of the data, while human oversight handles conflicting edge cases — far more reliable than manual redrawing, which is resource-intensive and prone to replicating existing mistakes into the central system of record.
Keeping humans in control
As autonomous systems make decisions at a scale and speed humans cannot replicate, engineers may struggle to understand and independently validate them. Human-readable network connectivity visualisation therefore becomes more important, not less: data transformation gives us machine-operational data, but at the cost of human readability.
The answer isn’t another manually maintained layer of “shadow” documentation. Instead, iNTERACTIVE SCHEMATICS™ can automatically generate high-level and low-level network diagrams directly from the same inventory data used for automation — providing a real-time visual representation from the single source of truth.
Network connectivity visualisation is now evolving from documentation into a control and validation layer between automated systems and engineers, turning trusted digital data into an interactive operational view to support design, planning, troubleshooting, maintenance, and service provisioning.
Trust before autonomy
Autonomous networks are not only about making machines more intelligent. They also require a trustworthy representation of the physical network and the human visibility needed to understand and validate manual and automated decisions.
As network operators move towards higher levels of autonomy, the strategic question is:
Do we have an effective, trustworthy and scalable way to convert, validate, reconcile and visualise the physical network data on which network operations depend?
DFG CONSULTING can help you answer that question.
We can assess a representative sample of your own data to identify quality gaps, transformation opportunities and potential process improvements — and determine what it takes to make your network data trusted and automation-ready.
Contact miha.usenicnik@dfgcon.si to arrange an initial assessment or meet us at Connected Britain 2026 on 9–10 September.
Miha Ušeničnik has spent more than two decades working across telecommunications, technology development and operational transformation.
He has held senior technical and management positions in telecom and technology companies, including responsibility for broadband network development and WiMAX systems, and contributed to national broadband policy as principal author of Slovenia’s Broadband Strategy.
At DFG CONSULTING, his focus is on helping network operators transform complex network data into trusted, structured information that can support more efficient operations, automation and AI.

Infineon Technologies, which describes itself as a global semiconductor leader in power systems and IoT, has announced the acquisition of India’s C2i Semiconductors, a technology company specialising in software-defined multiphase controllers and smart power stages for AI data centre applications.
Infineon says that C2i Semiconductors’ technology complements its portfolio of power semiconductors and power systems, enabling intelligent and scalable power delivery architectures from grid to core for AI servers and high-performance computing platforms.
The acquisition also strengthens Infineon’s position in power solutions for AI data centres and adds highly specialised expertise in software-defined power management to Infineon’s global R&D network. In addition, it expands Infineon’s engineering capabilities in India, where it currently has approximately 2,800 employees, and reinforces the country’s role as a strategic innovation hub.
Adam White, President of Infineon’s Power Systems (PS) division, explains: « This acquisition will further strengthen Infineon’s leadership in power solutions for AI data centres and create a new centre of excellence for digital power technologies in India, » adding: « C2i Semiconductors brings exceptional expertise in software-defined power management and system-level power architectures, backed by a proven highly experienced engineering team with decades of combined industry experience. With this acquisition, we will accelerate innovation in power delivery solutions for AI data centres, expand our capabilities in next-generation vertical power delivery architectures, and create significant value for our customers. »
Ram Anant, Founder & CEO of C2i Semiconductors, adds: « We founded C2i Semiconductors with the vision of bringing greater intelligence to power delivery systems and addressing the growing power challenges of AI infrastructure. Joining Infineon gives us access to world-class semiconductor technologies, manufacturing capabilities, and global customer relationships. Together, we can accelerate the development of software-defined power architectures and bring our innovations to customers worldwide. »
By adding intelligence to the power delivery architecture, Infineon says, software-defined solutions help data centre operators improve efficiency, reduce power losses, and support the increasing power density requirements of next-generation AI processors. C2i Semiconductors’ technology takes a system-level approach to power delivery, spanning the path from grid to core and enabling more intelligent and adaptive power architectures for AI infrastructure.
The transaction is expected to close in the third quarter of 2026.
Across the telecoms sector, operators, vendors and other suppliers are pushing towards renewable energy and sustainability goals with an uncommon unity. Given that operating a network requires a constant supply of power, it makes sense that to pivot towards cheaper and more sustainable sources of energy – but behind the talk, are companies truly taking action on their Net Zero goals?
The GSMA’s Mobile Net Zero Report 2026 examined industry progress on the broad goal of achieving Net Zero by 2050 and found that increased access to renewable energy is fundamental to achieving this. We spoke to Steven Moore, Head of Climate Action at the GSMA, to find out where progress is being made, and what more needs to be done.
The report mentions that a 45% reduction is required on the science-based pathway, but it’s looking like the sector might fall short of that by 2030. Why is the industry not on track? Further progress in Asia particularly is going to be essential to accelerate that – why is Asia so significant for this?
The steepness of the reduction curve is aligned to limiting heating to 1.5 degrees – effectively it means a 45% cut by 2030. Beyond that to 2040, there’s a project underway with the ITU to work out what the next stage of the science-based pathway will be, but the end goal needs to be Net Zero by 2050. We’ve had a 13% cut from 2019 to 2024, and that’s despite seeing a very big increase in both data traffic across networks and mobile connections. We’ve managed an overall global decrease despite effectively serving more customers and providing a greater service, but we are short – at about a 5% reduction in 2024, which is the last full year that we have data for. We need to be about a 7.5% annual reduction by 2030, so to hit that there needs to be an acceleration. There are two very significant regions to help us achieve that – they’re both in the same part of the world, but we separate them in the GSMA: the Greater China region and APAC more broadly. In terms of the number of connections and the electricity use across those two areas, the overall Scope 1 & 2 carbon emissions are really significant. What happens in those markets will determine whether we’re able to hit that 2030 global target. China has made fantastic progress on renewables; they’re adding more renewable capacity than the rest of the world combined each year, but still are also using a significant amount of coal to power electricity, and we’ve seen significant increases in electricity use by Chinese operators over the last few years. We have seen a drop; Chinese operators have started to purchase some renewable energy, so that’s helped, but the world is really watching China to see what happens to its emissions over the next few years. Overall they’re stabilising, potentially reducing, but then we’ve had this challenge with the energy crisis in terms of receiving things like oil and gas; is that going to mean that there’s more coal that’s used? The APAC region more broadly is also an interesting one because mobile connections are continuing to grow, whereas they’ve plateaued more in Europe and North America and other parts of the world. We also highlight in the report the potential growing investments in AI; that’s obviously quite uncertain.
AI’s power consumption is a controversy in itself – how is this impacting the industry’s Net Zero goals?
Some operators have made announcements about investments in AI; the very largest tech companies have made some extremely large announcements in terms of their financial investments into AI. There is a question mark around how much of this will actually end up being built out because of challenges around the chips and memory shortage, which we know is impacting the cost of mobile phones as well, and whether they can get sufficient power for these new data centres – that’s the other potential constraint. We’ve looked at what’s been announced by some of the biggest companies, and how telco announcements compare against those. Those are some of the headwinds to reductions over the coming years, but there’s significant uncertainty around those. We also talk about continued improvements in energy efficiency; we know that the rollout of 5G has helped, that switching from copper to fibre is also helping, and that switching off 2G and 3G legacy networks seems to support reducing network emissions in countries where they’ve been shuttered. We’re in the middle of developing 6G and we’re having lots of discussions around the sustainability of this. There’s also been an increase in renewable use across the sector – it was around 10% in 2019, now around a quarter of electricity used is directly purchased by operators. This is in addition to renewables that are already on grid worldwide, which operators get automatically by buying electricity from a country’s grid, but lots of operators go beyond this with specific investments – either buying renewable energy certificates or entering long term power purchase agreements. Operators are a good match for renewable energy providers as they want longer-term customers; operators can say that they need energy for the next 20 to 25 years, and these long-term purchase agreements have enabled the construction of several new renewable energy facilities worldwide because of the guarantees around the buying. We also see a lot of on-site renewables, particularly in off-grid locations or areas with a poor grid. This is challenging as there’s often a lack of available space; masts are in rented locations, and this restricts the amount of onsite renewable energy we’re able to generate as an industry. That’s never going to power more than a couple of per cent in terms of overall electricity demands, but where we can deploy it it’s essential.
The role of tower companies is particularly significant to emerging markets – the ownership structures are a bit different to mobile network operators, which in general are more publicly listed companies so there’s more transparency around their emissions, with annual sustainability reports. This is not generally the case with towercos – some of them publish their results, and are making good progress on reducing Scope 1, 2 and 3 emissions, Cellnex being a good example – but there are many where it’s less clear. We included some estimations of the amount of diesel used by tower companies in 2024 – around 2 billion litres – which is obviously a significant cost, and there are major environmental implications of the carbon emissions of 2 billion litres of diesel being burnt. We know that the 100 largest tower companies cover about 4 million sites around the world, so they’re a significant part of the market. What we also explored in the report was how well aligned the lease agreements are, i.e. the contracts between tower companies and mobile network operators, in terms of supporting some of the targets. 81 operators now have near-term science-based targets, but we see a smaller proportion of tower companies that have these targets as well. That’s a challenge for mobile network operators if the company that they’re contracting isn’t as aligned as they are in terms of reducing emissions and switching to renewables.
Operators have a degree of leverage here, but that’s largely going to be through how agreements are structured. Is there much of an appetite for gearing business models towards those that encourage decarbonisation among tower companies? The efforts of operators to reduce their emissions obviously are apparent, but if tower companies are not doing enough, the impact is going to be diminished.
That’s the big question mark: what are the different contract structures used across the industry, and are they supporting decarbonisation? That’s what we provide analysis around – we give examples of which are likely to work in the interests of the operators for reducing emissions, and others in which there’s not really any incentive for the tower company to reduce emissions. We highlight it as an issue across the industry, and explain how incentives might be better aligned – pointing to contracts which would work more in the interest of operators with targets, to say to them: “if you’re looking to renegotiate or when the contract comes to an end, you might want to consider restructuring it in a slightly different way, so that you and the tower company are on the same page”. We’re interested in engaging with our companies more: we’ve certainly spoken to them from the climate side. We want to send signals that this is where operators are, this is where the industry as a whole is moving to and see if we can have more of them get on board and support reduction efforts. We would love to see some more transparency around reporting of emissions because it helps us. We do this report every year, and there’s a data gap, so it makes it more difficult for us to understand where exactly emissions are going if we’re having to estimate and infer some of these figures.
Operators are inherently consumer focused; they feel that pressure but also a genuine concern and drive to pursue this. A lot of the emissions from the sector are Scope 3, i.e. supply chains, which encompasses towercos, so perhaps feel less pressure to be seen to be decarbonising or reducing emissions. How can that be addressed? How can we engage that side of the sector in order to start driving down carbon emissions across Scope 3?
This is this is one of the key challenges, particularly around Scope 3, but around how companies share these targets internally and make sure the organisation is moving in the same direction on them, because climate targets are so far-reaching they now are intersecting right across the organisation. Scope 1 & 2 emissions are focused on network operations, but Scope 3 is all about procurement, and operators obviously procure lots of different things, not just energy. There are conversations to have with device manufacturers and network equipment suppliers, and there are all sorts of other things that they might buy as well. We’re seeing some operators moving into selling other types of equipment, so having your procurement team fully up to speed in terms of what the climate targets are, and then engaging your suppliers, having that conversation to say, « We’re aiming for this reduction by 2030. Are you measuring your emissions? How are you managing them? Have you set your own science-based targets? Are you cascading that back into your supply chain?” Those are all fundamental questions that we see the leading operators [asking] and have quite a positive relationship with their suppliers around this, because they’re sending a signal of the direction they want to head in, but they’re also setting out a reasonable time frame for suppliers to respond and take action. We have seen some, particularly European operators, say to their suppliers, « If you don’t meet these requirements, then you effectively are deselected.” So there’s an incentive for them to act, and operators provide support, but there’s also there’s a hard backstop that if they don’t see movement, then they’ll look to choose others. That’s on the procurement side, but we see climate action targets cutting across into finance; when you’re making the business case for a particular switch in approach, you might be looking to raise money as well. We’ve seen green bonds be used quite extensively by operators where they want to make sustainable investments.
So transition planning needs to be fairly holistic even if procurement is one of the main pitfalls?
Overall, something that we worked on from the GSMA side that we published last year was guidance on climate transition planning. When you’re reducing emissions, you need to take a whole company approach to it – it doesn’t really work if you just have a sustainability team trying to work on this in isolation. You need to have all different departments across the company brought into it, and each of them taking responsibility for the area of the target that they’re managing. We see reducing emission size, the mitigation part, being just as important as the adaptation piece as well. Both of those form a climate transition plan: how are you reducing emissions? Obviously we’re trying to avoid changing the climate much more than we have done already, and then accepting that there is already a significant amount of climate change built in. So, what are operators doing to address that, and how can they make their networks more resilient? That’s also an area that we’ve been working on more with operators over the last few months to try and understand how are they addressing some of the bigger climate challenges that are now confronting them? We’ve seen enormously extreme weather events over recent years. The mudslide through Valencia, the flooding of the Rhine in Europe, the U.S. in terms of wildfires, which are now becoming much more common in Europe. A third of Pakistan was underwater a couple of years ago. Southeast Asia is continually battered by typhoons. For operators, it’s business as usual in terms of keeping a network running, but there are now climate events, weather events that were completely unexpected. Portugal had its first very strong storm at the beginning of this year, with winds in excess of 80 to 100 miles an hour. That wasn’t even part of their risk register because it had never happened before. That’s also something else that we touch on in the report, looking at how the industry is addressing this challenge and what some of the potential costs might be of future damage around this, because we can see that’s likely to increase in the future.
What’s the impact of data centres? Are we only factoring in operator data centres in terms of the emissions? What about non-operator data centres?
We’ve looked at what the hyperscalers have announced and the type of energy use that will entail. In comparison, telecom operators are a small fraction. Geographically, the Middle East and APAC regions are more likely to be building AI data centres – Japan, South Korea, Malaysia, Singapore, although it has some energy challenges, and the Middle East. We’re not seeing it so much from operators in Europe, North and Latin America. Some operators are building AI data centres but not to the same scale. Critically, the scale of telecom operator AI data centres is much smaller than hyperscalers. Given that 81 operators are aiming for science-based targets where they’re building data centres, it’s much more likely to be powered by renewable energy as they want to hit these targets. We will evaluate this over the next few years, seeing how data centre buildout will affect our energy usage as a sector, and how many are being powered by renewable energy or other sources. One of the benefits of powering them with renewables is that they’re actually very cost competitive, particularly in certain parts of the world, and a renewable energy installation – a wind farm or a solar farm – can be quick to construct, which is a challenge at the moment in terms of how quickly can you plug into a new energy source or if there’s available energy on the grid, so this seems to be one of the biggest constraints in terms of building these new data centres. Given some of the memory and power challenges, as well as planning constraints, we can see policymakers are hesitant. We’ve seen local pushback, particularly in the U.S. where very big installations have been built. Local electricity prices have gone up, so we’re starting to see opposition to building data centres. So, quite significant uncertainty around announcement versus what will be the actual build out in the future.
We’ve seen pushback in terms of the ability to connect to the grid and the reliability, but also the incentives that have been offered to build out data centres – countries are realising they don’t necessarily have the ability to meet demand. The report notes that in terms of renewable energy powering data centres, operators are consuming about 300 terawatt hours of electricity in 2024, of which 70 was renewable, so less than a third of the total usage.
That’s of purchased renewables. I should clarify because it’s tricky to come up with an overall figure because if you look at electricity produced globally, around a third of it on grids is from renewable sources – wind and solar, also hydro power. We add that figure to the purchased one, but there is a bit of overlap so the accounting becomes tricky. We specify the amount that’s purchased directly by operators, but there will be an addition of what’s already on the grid. Operators in general want to use more renewable energy; the industry is a very eager purchaser of renewables, and that is quite a challenge because many markets around the world don’t have liberalised energy markets. They might have one single provider which might offer you a green tariff that is more expensive than the normal tariff, whereas in a liberalised energy market like the UK and other European markets, you can directly contract with a renewable energy generator, and you can enter into a long-term power purchase agreement. One of the recommendations for policymakers and regulators is to improve access to renewable energy for mobile network operators. We need a fully liberalised energy market because we need to have wheeling in the technical part – wheeling of electricity across the grid, because we have many sites across the country, unlike a data centre; you can build a solar farm next to the data centre, plug it in, and then you’re powering that data centre from renewables. We can’t do that because most of our electricity flows through the grid, so we need to have a system in which we can match our electricity demand through a market design, and tell an energy generator “we use this amount of energy, we’re going to purchase it from a renewable energy generator, and they can provide that to us.” These are technical conversations that we’re having with policymakers and regulators in certain countries. We’ve had some really positive discussions with the Malaysian government over recent years, and they are moving in that direction and making it easier for corporates to purchase renewable energy. But that is a significant challenge for us in quite a few markets, and particularly developing markets.
Your statistics show that a lot of renewables are purchased in Europe and the US, but in Latin America the figure is 45% – is it lower in Asia and Africa? I imagine the energy markets there are not as liberalised as would be ideal in this scenario.
No, and in APAC, there’s a challenge around one single monopoly provider. There also is that situation in Africa, but there’s the added challenge of a lack of a grid in many cases. We see so many off-grid sites, and obviously that’s where we see a significant amount of diesel use. Or if there is a grid, it’s not reliable enough, so you need to have a diesel generator back up. We’re very fortunate in that recent years there’s been a huge amount of technological development in solar panels, and their efficiency, and then also battery development in general in terms of storage, and also the cost of batteries. That’s all very helpful in terms of looking at alternatives for diesel generators. Fuel cells are also another option that I know some operators are exploring as well; there are still some challenges around security though, in that where they have been installed, there’s been theft associated with some of them because they’re seen as quite valuable assets. There are things that operators want to do; they’re moving in that direction, but there are some challenges in order to achieve that.
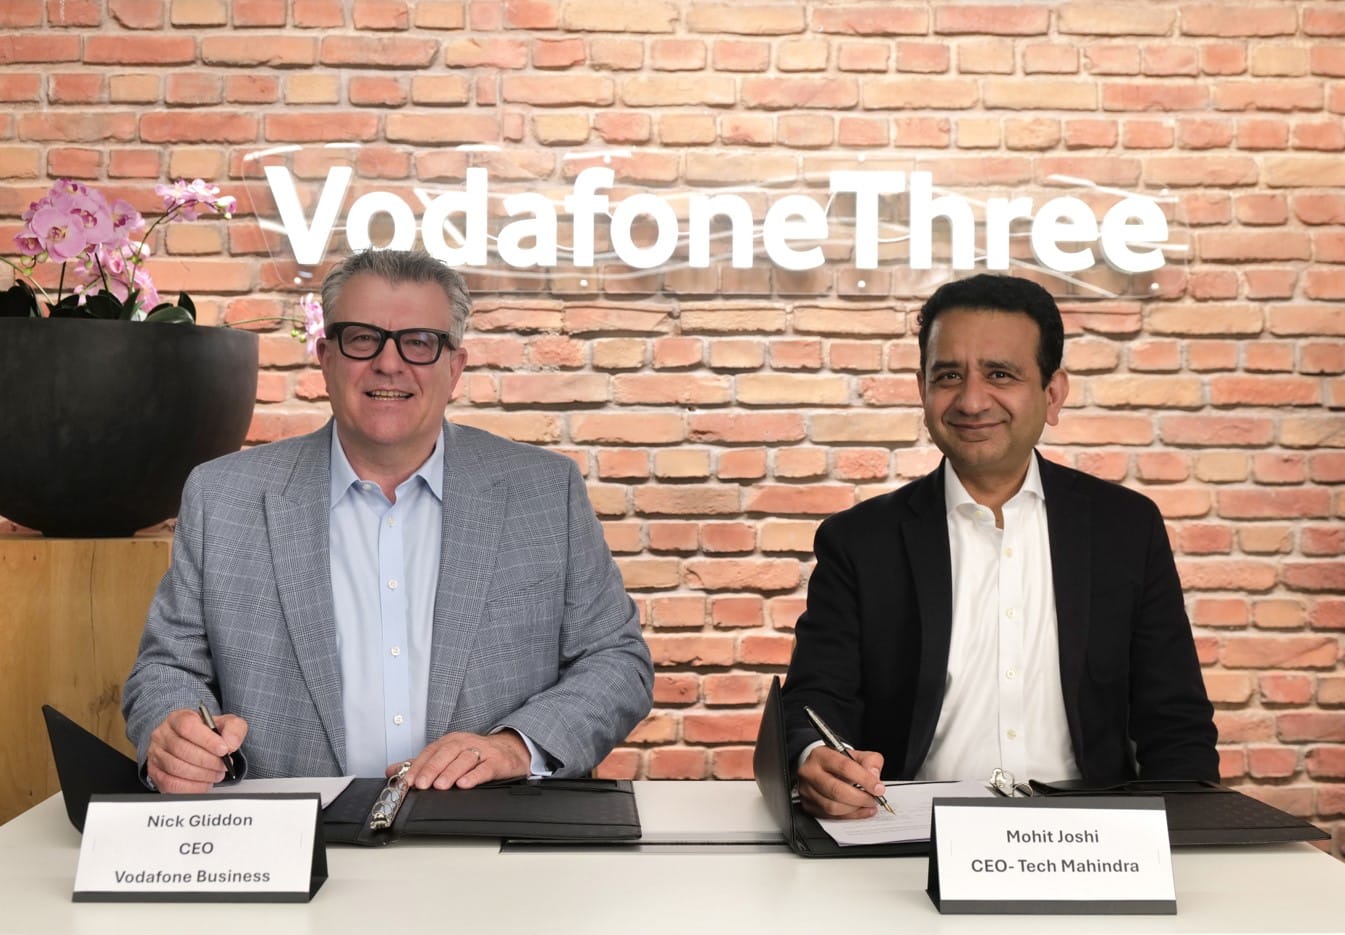
Vodafone Business, the enterprise arm of VodafoneThree, has announced a partnership with Tech Mahindra, a leading global provider of technology consulting and digital solutions to enterprises across industries, reinforcing its commitment to helping organisations across the UK accelerate digital transformation and realise the benefits of emerging technologies.
Building on VodafoneThree’s £11bn investment to create the UK’s best network for business – and provide organisations with the secure, resilient and scalable digital foundations they need to modernise and grow – the agreement establishes a structured model for executive engagement, co-innovation and go-to-market collaboration. It will enable both organisations to identify and develop opportunities where their complementary capabilities can help customers simplify operations, modernise technology environments and deliver measurable business outcomes.
By combining Vodafone Business’ enterprise and digital infrastructure capabilities with Tech Mahindra’s expertise in AI-led technology transformation, systems integration, digital engineering and managed services, the two organisations will develop industry-led propositions for UK customers. The collaboration will leverage AI, automation, private 5G, IoT, cloud and data to modernise operations, strengthen resilience, accelerate digital adoption and unlock new business models.
Tech Mahindra has a strong UK presence, combining local market expertise with global capabilities in AI, digital engineering, cloud and data. Guided by its “AI Delivered Right” strategy, Tech Mahindra helps organisations move AI from experimentation to enterprise-scale adoption and measurable outcomes. Through this partnership with Vodafone Business, both organisations will combine their strengths to help UK businesses modernise operations, strengthen resilience and accelerate AI-led growth.
The agreement supports Vodafone Business’ broader strategy to build a strong ecosystem of specialist partners, giving customers access to the expertise and capabilities they need at each stage of their digital transformation. By bringing together enterprise services, digital infrastructure and technology expertise, Vodafone Business is helping organisations adapt to changing market demands, improve operational performance and drive sustainable growth.
Nick Gliddon, Business Director, VodafoneThree, commented: “This partnership with Tech Mahindra brings together the capabilities organisations need to move faster in a complex digital landscape. By combining Vodafone Business’ connectivity, technology and security expertise with Tech Mahindra’s specialist transformation capabilities, we’re strengthening our partner ecosystem and giving customers access to integrated solutions across cloud, AI, cyber security and digital transformation – helping them cut through complexity, build resilience and become more agile, competitive and future-ready.”
Harshul Asnani, President and Head of Europe Business, Tech Mahindra, said: “Tech Mahindra has a deep heritage in telecommunications and extensive experience helping enterprises modernise complex technology and operating environments. This framework with Vodafone Business brings together our complementary strengths to help UK organisations accelerate AI-led transformation. By combining AI, automation, digital engineering and industry expertise, we will help enterprises modernise networks and operations, build resilient digital ecosystems and unlock measurable business outcomes at scale.”
How is the UK telecoms market changing in the UK? Join the discussion at Connected Britain 2026, the UK’s largest digital economy event
Today, Huawei and HP Inc. announced the signing of a multiyear global patent cross-licensing agreement, including license to HP Inc. for certain Huawei WiFi patents. This milestone agreement not only reflects the companies’ cooperation in the field of intellectual property licensing but also recognizes Huawei’s innovation capabilities and core technological strength as well as HP’s position as a global leader in computers and peripheral equipment.
Alan Fan, Huawei’s Chief Intellectual Property Officer, stated, “Huawei is pleased to reach this patent cross-licensing agreement with HP Inc. This agreement is a strong testament to Huawei’s persistent independent innovation in cutting-edge fields in Information and Communications Technology (ICT). Through patent licensing, Huawei shares its innovation with the industry, particularly in the area of standardized technologies, which brings leading technological experiences to consumers worldwide.”
Steven Geiszler, who represented Huawei in the negotiations, stated: “This is another successful licensing of Huawei patents, particularly in the area of standardized Wi-Fi technologies—while obtaining valuable reciprocal patent rights from HP Inc. I appreciate the professionalism and courteousness shown by HP’s negotiation team during this project.”
“This is a standard-essential patent license covering Wi‑Fi technology – something used broadly across the industry and routine for companies whose products connect to Wi‑Fi. It is not new, does not represent a broader strategic or commercial relationship, partnership, or collaboration with Huawei,” said HP in an emailed statement.
Wi-Fi has become one of the most widely used wireless technologies in the world, connecting homes, schools, hospitals, offices and public spaces. Each generation of the standard is developed openly, drawing on technical contributions from companies across the industry, and is then made broadly available to implementers.
Although lacking the speed and throughput of newer generations, Wi-Fi 4 and 5 are still widely used, providing reliable networking for less demanding applications.
High speed, large capacity and lower energy consumption enable Wi-Fi 6 to deliver multiple high-definition video streaming, gaming and AR/VR services alongside legacy broadband and IoT devices such as laptops, refrigerators, cameras, doorbells, thermostats, and lightbulbs—all with a single wireless router.
Wi-Fi 7, building on Wi-Fi 6, delivers higher throughput, lower latency, and more reliable Wi-Fi connectivity. These enhancements enable an exceptionally smooth experience for 8K video, gaming, AR/VR, remote work, online video conferencing, and cloud computing.
Together, these advances and applications have made reliable wireless connectivity part of the basic infrastructure of everyday life — supporting remote healthcare, digital education, and more energy-efficient homes and workplaces. Huawei has played a significant role in contributing to the development of Wi-Fi technologies over successive generations and makes the resulting technologies available publicly, so that innovation created in one place can benefit users everywhere.
To learn more about patents and licensing, here is Huawei’s Chief Intellectual Property Officer Alan Fan answering common questions on the topic from the internet.

EXA Infrastructure has added an interesting new longhaul route to its European network. They have built out a new terrestrial link between the Spanish markets of Barcelona and Bilbao. … [visit site to read more]
China has approved its first private-sector commercial trial for satellite Internet of Things (IoT) services, granting a permit to Zhejiang Geespace Technology as part of what are being described as broader efforts to open the country’s satellite communications market to private capital.
Indeed in its approval notice, the country’s Ministry of Industry and Information Technology (MIIT) highlighted satellite IoT as an important complement to broadband satellite services, noting that the trial would help pave the way for further private-sector participation in China’s commercial space development.
MIIT has granted Geespace, the commercial space subsidiary of electric vehicle giant Geely, a two-year trial period.
Geespace is a global satellite communications service provider dedicated to the construction and operation of a low Earth orbit (LEO) communication constellation. It independently designs, develops, deploys, and operates the global LEO satellite Internet of Things (IoT) constellation Geesatcom.
Geespace will provide low-power, wide-coverage connectivity across sectors including smart transport, marine fisheries, energy, and water infrastructure.
Geespace is now the first private Chinese company to secure approval for a satellite IoT commercial trial, though the South China Morning Post notes that in May, MIIT issued the country’s first satellite IoT trial permit to Beijing Guodian High-Tech Technology, an entity backed by state-owned China Mobile, the nation’s largest wireless carrier.
Founded in 2018, Geespace has launched around 64 satellites. Some reports suggest its long-term plans are to deploy a constellation exceeding 5,600 satellites.
Geespace is also pushing into international markets, saying that it has had trials with telecoms operators in more than 20 countries across the Middle East, Africa, Southeast Asia, Central Asia, South Asia and Latin America.

A bit of AI, a bit of last mile fiber, and a regulatory hurdle: … [visit site to read more]