The economics of fixed wireless access have always been a story of two costs: the cost of reaching a subscriber, and the cost of serving one once reached. Fiber dominates the first conversation — trenching, permitting, and a per-home-passed bill that runs into the hundreds or thousands of dollars per location. FWA’s enduring pitch has been that it collapses the “reach” cost by spending spectrum instead of construction. What has quietly held FWA back in the places where it matters most is … [visit site to read more]
Operator Ooredoo Qatar has announced the launch of Qatar’s first 5G+ mobile network, building on the capabilities of 5G standalone, the network Ooredoo Qatar was the first to deploy.
The operator says that the 5G+ (a term sometimes used for 5G Advanced) network supports increasingly demanding digital applications, with faster speeds, greater network capacity, and lower latency.
These improvements, it adds, enable more devices to connect and exchange information efficiently, while shorter response times support applications such as real-time equipment monitoring and automated processes.
For consumers, Ooredoo continues, the 5G+ network supports enhanced streaming, more responsive gaming and seamless connectivity on the move.
Ooredoo has deployed this new technology across different locations in Qatar, though these are not specified in the announcement. It is commercially available through mobile broadband in areas covered by the 5G+ network.
For businesses, these capabilities provide a foundation for more efficient operations and better-informed decisions. Enhanced network reliability and performance support real-time monitoring, AI-enabled services, and complex digital workloads.
Network slicing, which allows connectivity to be tailored to specific applications, is another opportunity enhanced by the 5G+ network, while 5G advanced networks and edge computing can support mission-critical applications that require rapid responses.
Expanded IoT capabilities also support industrial sensors, asset trackers, and utility meters, enabling automation, intelligent operations, and future smart city services.
This is another first for the company. Sheikh Ali bin Jabor bin Mohammad Al Thani, Chief Executive Officer of Ooredoo Qatar, explains: “From launching the world’s first 5G network in 2018 to deploying Qatar’s first 5G Standalone core network, we have consistently advanced connectivity. This launch marks the next step in that journey, supporting the next generation of digital services across Qatar.”
Large-scale data centre growth in India appears to be accelerating, with recently announced deals or plans including big names such as CtrlS Datacenters, Submer, BSNL and Google, but some public discomfort has been expressed about the rollout in Andhra Pradesh.
CtrlS Datacenters has signed a letter of intent (LoI) with the government of Bihar, a state in eastern India, to invest INR100 billion (an estimated US$1.05 billion) to set-up a 150 MW hyperscale AI factory in Bodh Gaya, one of Buddhism’s most important pilgrimage sites. CtrlS has also formally inaugurated its INR4 billion (about us$42 million) AI and cloud-ready data centre in the capital Patna.
Meanwhile, global IT services and digital infrastructure provider Submer and BSNL Tower Corporation Limited (BTCL), a wholly owned subsidiary of operator BSNL, have signed a memorandum of understanding (MoU) to explore the development of sovereign, AI-ready data centre infrastructure across India.
Submer and BTCL will jointly assess opportunities spanning GPU-as-a-service (GPUaaS), sovereign AI cloud infrastructure, edge and micro-edge data centres and large-scale data centre projects of up to 20 MW.
Under the MoU, Submer will apply its expertise in integrated data centre architecture, liquid cooling, thermal management and high-density computing. BTCL will coordinate access to relevant BSNL premises and data centre facilities for technical and commercial feasibility studies. It will also support connectivity, regulatory alignment, and engagement with government and enterprise stakeholders.
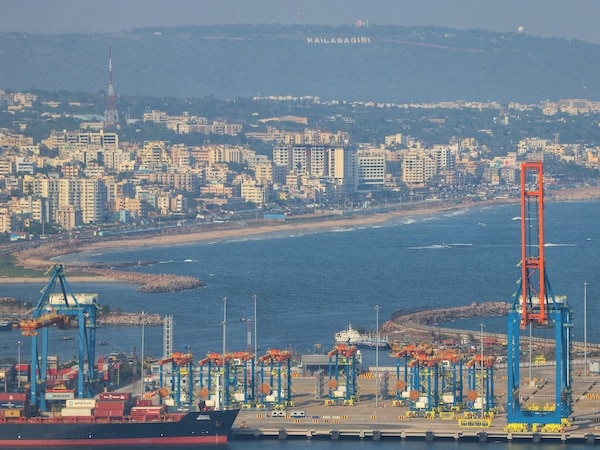
However, in Visakhapatnam in Andhra Pradesh on India’s southeast coast, where the US$15 billion construction of Google’s largest data centre outside the United States is under way, such developments are being questioned.
Visakhapatnam is a landing point for submarine internet cables linking the country to Singapore, so, for India, the location of the 600-acre site is ideal. And other tech sites are planned in the area. Indeed, a joint venture between multinational conglomerate Reliance Industries, investment management company Brookfield and data centre platform provider Digital Realty, is investing US$11 billion in another AI data centre in Visakhapatnam.
Many residents fear the Google data centre will strain water and power resources, damage the environment and bring too few jobs in return, fears that Google and local government suggest are unjustified; they argue that many direct and indirect jobs, as well as significant economic activity, will result.
In response to comments about water supply, Google has said it will deploy ‘advanced’ air cooling technology to ease water use at the data centre, while the state plans six 1.2-gigawatt nuclear power plants to manage energy demand.
Nevertheless, news reports suggest that activists in Andhra Pradesh are demanding a moratorium on new data centres across the state until independent environmental and social impact evaluations are published.
However, more such developments are highly likely. India has only about 3% of global data centre capacity, according to government figures, and wants more. It has rolled out a variety of incentives to attract big tech companies, including tax cuts.
By Jabbor Kayumov, Chief Executive Officer, Beeline Kazakhstan
Kazakhstan’s geography has always shaped its economics. It is the ninth-largest country in the world, with communities spread across vast steppe, desert and mountain terrain. For generations, distance has influenced the cost of connecting a clinic, a school, a farmer or a small business to markets and essential services.
Digital infrastructure is beginning to change the economics of that distance. But a signal bar alone is not digital inclusion. Connectivity creates lasting value only when three conditions come together: people can reach it, the technology can understand them, and the services available through it allow them to do something meaningful.
I lead Beeline Kazakhstan, and across my career with digital operators in Central Asia, South Asia and the Caribbean, I have seen very different markets confront the same challenge. Demand for digital participation almost always arrives before the infrastructure that enables it. A rural clinic, a family farm or a first-time online seller does not need to be persuaded that connectivity matters. They need access that is reliable, affordable and relevant to their lives.
The first requirement is reach
Terrestrial mobile networks will remain the backbone of connectivity. In Kazakhstan, Beeline has extended its network to villages with populations of around 100 people and has used solar power for base stations beyond the electricity grid. Yet in a country of this scale, the economics of a conventional tower will not close every remaining coverage gap.
That is why we are working with Starlink Direct to Cell to introduce satellite-to-phone connectivity in areas beyond the reach of terrestrial networks, beginning with messaging and expanding to data in a later phase, subject to the required approvals. The technology is designed to connect ordinary compatible mobile phones without a separate satellite terminal. It is not a replacement for terrestrial infrastructure. It is an extension of it, particularly where distance makes traditional deployment slow or uneconomic.
The real breakthrough will not be a successful demonstration. It will be a service that works reliably and can be sustained at scale. Technology must change not only the map of coverage, but also the economics of providing it.
The second requirement is relevance
Even universal coverage would be incomplete if the digital tools available through it could not properly understand the user’s language and context. Many of today’s leading AI systems perform best in languages with the largest digital footprints. Kazakh, like many national languages, remains underrepresented in the data on which global models are trained.
KazLLM is therefore more than a technical milestone. Developed through a national collaboration coordinated by the government and led by the Institute of Smart Systems and Artificial Intelligence at Nazarbayev University, with contributions from QazCode, Beeline Kazakhstan and Astana Hub, it gives developers an open-source foundation on which to build services in Kazakh. The larger point is simple: people should not have to leave their language behind to participate fully in the AI economy.
Compute capacity matters as well. Beeline Kazakhstan is building Hyper Cloud, a Tier III data center in Almaty targeted to come online by the end of 2026. It will provide domestic capacity for enterprise, cloud and AI workloads and help organizations keep sensitive data within Kazakhstan. The purpose of sovereign infrastructure is not isolation. It is the ability to participate in global technology with greater resilience, capability and agency.
The third requirement is utility
A connected person is not necessarily an included person. A signal reaching a remote community has limited impact if the person receiving it cannot open an account, receive a payment, access a public service, learn a new skill or sell a product beyond the local market. For a farmer, the value of connectivity may be payment for a harvest. For a small retailer, it may be accepting a digital payment without investing in expensive equipment. For a student, it may be accessing a course or paying a fee without traveling to a branch.
This is why connectivity, trusted digital identity, payment infrastructure and locally relevant services should not be planned as separate agendas. Each increases the value of the others. Kazakhstan’s work on the digital tenge is one example of financial infrastructure evolving alongside communications networks. The opportunity is to connect these layers so that access can translate into participation in the economy.
That also changes how we should think about investment. VEON has announced its intention to invest an additional $1 billion in Kazakhstan over the next three years. Capital on that scale must do more than add equipment. It should expand the number of people and businesses able to participate in the digital economy, strengthen domestic technological capability and create services that customers choose to use every day.
For that model to endure, inclusion must also be commercially sustainable. Remote communities cannot depend indefinitely on pilots or one-off interventions. Satellite connectivity can improve the economics of reach. Local-language AI can make technology useful to a wider population. Digital financial services can turn access into everyday economic activity. Built together, these capabilities reinforce one another.
Kazakhstan’s experience points to a broader lesson for other large and sparsely populated markets: digital inclusion must be built as a complete system. Reach without relevance leaves people behind. Relevance without useful services produces novelty rather than impact. And services without resilient infrastructure cannot scale.
Distance will remain a fact of Kazakhstan’s geography. It does not have to remain a limit on opportunity. If we build reach, relevance and utility together, a customer in a remote community is no longer at the edge of the digital economy, but fully part of it. That is the future we intend to help build.
Jabbor Kayumov was appointed Chief Executive Officer of Beeline Kazakhstan in April 2026.
Before his appointment, he served as Chief Executive Officer for the Telco Business at Beeline Kazakhstan. Prior to that, he held leadership roles across multiple international companies, including serving as CEO of Ncell in Nepal and leading Digicel’s operations in Jamaica and Trinidad & Tobago, where he oversaw their transformation into digital operators. He also served as CEO of Beeline Tajikistan. His leadership experience spans strategic transformation, commercial growth, organizational development, and digital innovation.
IFS has launched IFS Intelligence, an AI product that lets industrial businesses query operational data, investigate issues and prepare actions through a conversational interface.
The product draws on live data from IFS and connected third-party systems, including information on assets, work orders, schedules and operational history. It can recommend actions and prepare them for approval, with controls based on each business’s rules and permissions.
IFS Intelligence includes three components: Cowork, for querying data and preparing actions; Loops, which runs defined workflows in the background and escalates tasks when human judgement or approval is needed; and Runway, which uses plain-language requirements to support IFS software migration, configuration and extension.
Customers can also save successful queries as reusable Skills or create Lenses, which provide live views of operational data. Cowork can connect to systems such as Microsoft 365 through the Model Context Protocol.
IFS cited crane rental and heavy lifting company Sims Crane & Equipment as an early user. The company said staff can query fleet data to identify suitable cranes for customer requirements and improve fleet utilisation.
The deal is expected to boost the lifespan of the company’s aging submarine cables around Svalbard
Space Norway has announced a new deal with Ciena to modernise the Svalbard Undersea Cable System and its upcoming Arctic Way cable system with the latest optical technolgy.
The deal will see Space Norway’s existing infrastructure upgraded with Ciena’s latest optical technology, including the Ciena 6500 Optical Platform, WaveLogic 6 Extreme, Spectrum Sharing, and the Navigator Network Control Suite.
The same technology will also be used in the upcoming Arctic Way Cable System.
This, the company said, will ‘expand the operational lifespan’ of the Svalbard Undersea Cable System and expanding secure, high-resilience connectivity across the Acrtic region.
“Reliable connectivity is essential in the Arctic, where our infrastructure supports critical activities and demanding operational requirements,” said Pia Birgitte Bruhn, acting Vice President of Cable Systems at Space Norway. “By working with Ciena, we are extending the operational life of our existing Svalbard cable systems while preparing Arctic Way for service. This investment will strengthen the resilience and capacity of our subsea network and support the region’s long-term connectivity needs.”
Space Norway is a satellite company owned by the Norwegian state that operates hybrid infrastructure, comprising satellites, teleports, fibre networks, and subsea cables. The company provides mission-critical communications relied upon by research, scientific, and national security organisations.
The company operates the Svalbard Undersea Cable System, which began service in 2004 and spans roughly 2,714 km from Breivika in northern Norway to Longyearbyen, Svalbard’s largest town.
Currently, Svalbard only has one other submarine cable: the Longyearbyen–Ny-Ålesund route on the west of the archipelago operated by Sikt, the Norwegian Agency for Shared Services in Education and Research.
However, this will change in the coming years through the deployment of Space Norway’s upcoming Arctic Way system. Announced in 2025, will connect Bodø, Norway, to Longyearbyen, with separate branch to the remote island of Jan Mayen, home to Beerenberg, the most northern active volcano in the world.
While Svalbard and Jan Mayen have few or no permanent residents, they remain of high strategic importance for Norway. Svalbard, for example, notably hosts SvalSat, a crucial satellite ground station that monitors the Arctic region for which reliable backhaul is crucial.
Keep up to date with all the latest telecoms news from around the world with the Total Telecom newsletter
Global smartphone shipments fell 20% year-on-year in the third quarter of 2026 as rising memory chip costs pushed up device prices and weakened consumer demand, according to Counterpoint Research.
The decline marked the weakest third-quarter performance in 14 years, although it was in line with the research firm’s forecast. Average selling prices (ASPs) have risen 20% so far this year as manufacturers pass on increases in DRAM and NAND memory costs to consumers.
Counterpoint Research senior analyst Shilpi Jain said the market was only beginning to feel the full impact of the memory crisis, with the third quarter representing the second consecutive quarter in which manufacturers faced its effects.
Consumers are responding by delaying upgrades and considering refurbished devices, while the premium segment has proved comparatively resilient.
Samsung regained the top position in the market with a 23% share, despite a 3% year-on-year decline in shipments. The South Korean manufacturer focused on premium models, including foldable devices, which saw strong initial demand.
Apple followed with a 22% share, up from 18% a year earlier, despite a decline in shipments. Counterpoint attributed the fall in volumes partly to the absence of a base iPhone 18 variant and rising prices.
Xiaomi suffered the sharpest decline among the leading vendors, with shipments falling 30% year-on-year and its market share dropping from 14% to 10%. The Chinese manufacturer, known for its affordable devices and thin margins, has tightened shipment plans to avoid selling devices at uneconomical margins amid rising component costs.
Oppo and Vivo also recorded shipment declines of more than 20%, with market shares falling to 9% and 8%, respectively.
Counterpoint expects market conditions to remain challenging for the rest of 2026 as manufacturers prioritise profitability over shipment volumes. Rising component costs are putting pressure on both vendors’ margins and consumers’ purchasing power. Manufacturers are expected to continue cutting production, reducing the size of their product portfolios and placing greater emphasis on premium devices as memory supplies remain constrained.
A recovery in shipment volumes is unlikely until component costs ease. Counterpoint has previously forecast that this improvement may not begin until late 2027.
We use cookies to personalise content and ads, to provide social media features and to analyse our traffic. We also share information about your use of our site with our social media, advertising and analytics partners. View more
Cookies settings
Accept
Privacy & Cookie policy
Privacy & Cookies policy
Cookies list
Cookie name
Active
Conditions légales
Introduction et qui nous sommes
118812.fr met en relation des spécialistes du monde entier par le biais d'événements, de renseignements et d'éditions savantes. Nous sommes une société du FTSE 100 et notre réseau de marques internationalement respectées aide les gens à travailler plus intelligemment, à prendre de meilleures décisions et à se développer sur des milliers de marchés spécialisés. Les données et les informations sont au cœur des activités de 118812.fr, et nous prenons au sérieux les questions de confidentialité des données. Nous respectons nos relations avec les clients, les visiteurs, les sponsors, les exposants, les fournisseurs et les collègues, ainsi que la confiance qu'ils nous accordent pour la conservation de leurs données personnelles.
Contrôleurs de données de 118812.fr
Cette politique de confidentialité explique comment les membres du groupe 118812.fr collectent, utilisent et protègent les informations personnelles à travers nos marques. Les références à "nous", "notre" ou "nos" renvoient au contrôleur 118812.fr concerné qui traite vos informations personnelles.
118812.fr est structuré en cinq divisions opérationnelles :
Au sein de ces divisions, il existe des entreprises sectorielles et des marques de produits, d'événements et de services. En général, lorsque nous interagissons avec vous, c'est par le biais de l'une de ces marques. L'entité juridique du groupe 118812.fr responsable des données personnelles (désignée comme le contrôleur des données dans l'UE et désignée comme le contrôleur 118812.fr dans la présente politique de confidentialité) sera l'entité indiquée sur les formulaires de réservation, les formulaires Web et les contrats ou les factures. Différentes entités juridiques de 118812.fr sont responsables de différents événements et produits. Pour mettre à jour vos informations personnelles ou vos préférences en matière de marketing, contactez les équipes de marketing de nos divisions énumérées ci-dessous. Pour toute question ou plainte concernant la confidentialité des données, vous pouvez vous adresser à l'équipe 118812.fr Privacy via notre formulaire en ligne.
Couverture internationale et variations
118812.fr opère dans plus de 20 pays, qui ont chacun des lois différentes sur la protection des données. La présente politique de confidentialité s'applique à toutes les activités de 118812.fr dans le monde, sauf dans la mesure où il existe une exigence spécifique à un pays qui la complète, comme indiqué dans le menu de gauche.
Ce que nous recueillons
Cette section vous indique quelles informations personnelles nous pouvons recueillir lorsque vous utilisez nos produits et services, et quelles autres informations personnelles nous pouvons recevoir d'autres sources. Dans la présente politique de confidentialité, les informations personnelles désignent les types de 118812.frtions personnelles qui peuvent être collectées et utilisées, notamment : Les coordonnées, telles que le nom, l'adresse électronique, l'adresse postale et le numéro de téléphone.Informations sur l'éducation, la nationalité et la professionles noms d'utilisateur et les mots de passeCommentaires, réactions, messages et autres contenus soumis, y compris les informations relatives aux enquêtes.Intérêts et préférences de communication, y compris les autorisations de marketing, le cas échéant.Informations de localisation, telles que celles fournies par une application mobileInformations de vérification de l'identité, telles que les détails du passeport, afin de se conformer aux obligations légales dans certains pays et de fournir des lettres d'invitation de visa, le cas échéant.Informations sur l'utilisation du site web et des communications, telles que la correspondance et les détails de votre utilisation de notre site web et de nos services obtenus par le biais de cookies ou d'autres technologies de suivi.
Ces informations personnelles concernent les catégories de personnes suivantes :
Prospects, contacts clients, abonnés et utilisateurs en ce qui concerne nos services et produits ;Visiteurs, sponsors, exposants et conférenciers lors de nos événements ;Les professionnels figurant dans les produits numériques et imprimés, tels que les détails des cadres supérieurs mis à disposition par les produits de renseignement, les recherches et les publications.les auteurs, éditeurs et réviseurs de nos publications.les contacts de nos prestataires de services et partenaires commerciaux.Informations personnelles sensibles